Acquisition is where investment returns are made or lost. Overpaying for an asset — even a quality asset in a strong market — compresses returns in ways that years of excellent management cannot fully recover. We have one standard for every acquisition: the conservative underwriting scenario must produce an acceptable return. Not the base case. Not the upside. The conservative case. If that standard cannot be met, we walk away.
This discipline is not caution for its own sake. It is the mechanism that has protected every dollar invested through Steve Ford across every market cycle including the 2008 downturn, the 2016 acceleration, the 2020 disruption, and the 2022-2024 rate cycle. The discipline is what allows us to offer investors returns with confidence rather than aspiration.
Opportunities enter the Steve Ford acquisition pipeline through three channels: our decade of Atlanta broker relationships (who call us before listing), our proprietary data-driven screening of on-market properties for below-market indicators, and direct outreach to identified property owners in target submarkets.
Before committing resources to full underwriting, every opportunity is assessed against five non-negotiable criteria: submarket demand confirmed, acquisition price within cap rate target, property class consistent with strategy, no structural defects that cannot be priced, and a clear exit thesis. Deals that fail any criterion are declined without further analysis.
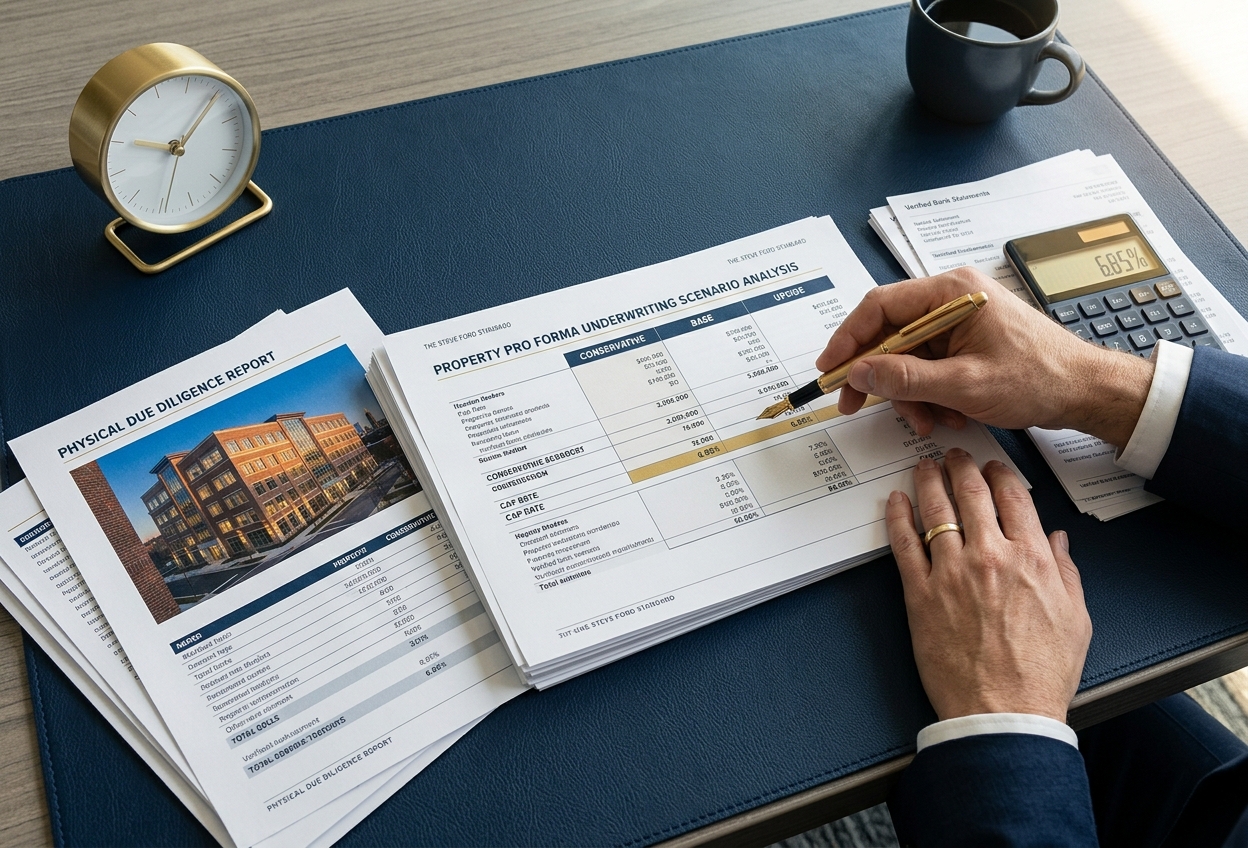
Opportunities that pass the initial screen receive a complete underwriting across three scenarios. Conservative: rents 10% below projection, expenses 10% above projection, exit cap rate expanded by 50 basis points. Base: market projections. Upside: moderate rent growth, operational improvement, cap rate compression at exit. The conservative scenario must be acceptable before proceeding.
Physical inspection (licensed inspector plus Steve Ford's own team walk). Financial verification (actual rent rolls, 12 months of bank deposit confirmation, expense documentation). Legal and title review (full title search, lien check, zoning confirmation). Market validation (comparable rental confirmation, competing supply analysis). Operator assessment (where applicable).
Steve Ford uses acquisition criteria-derived pricing — our maximum offer is determined by the numbers, not by competitive pressure. We will outbid the market in specific situations where our operational capabilities create a value differential that competitors cannot replicate (value-add execution, relationship with specific tenants, renovation capability). We will not overpay because the deal is competitive.
Prior to signing a purchase contract, the investment opportunity is presented to qualifying investors in a formal package: complete underwriting, due diligence summary, market analysis, renovation scope and budget (where applicable), and exit thesis. Investor questions addressed before capital commitment.
Purchase contract executed. Title company engaged. Lender notified for appraisal scheduling. Steve Ford's legal team coordinates closing documents. International investor entity and FIRPTA documentation prepared through Corporate World. Closing coordinated for minimum gap between investor capital commitment and close.
Within 72 hours of closing: property management engaged or confirmed, renovation scope finalised, contractor mobilisation scheduled (where applicable), and first investor update issued. The acquisition-to-operations handoff is managed by the same team that sourced and underwrote the deal.
| WHAT WE NEVER DO | WHY IT MATTERS TO INVESTORS |
|---|---|
| We never acquire a property where only the upside scenario produces acceptable returns | Every acquisition has downside risk. An investment that requires the upside to justify itself has no margin of safety. Investor capital deserves a margin of safety. |
| We never use leverage above 65% LTV on commercial acquisitions or 70% on residential | Higher leverage amplifies losses in a downturn as severely as it amplifies returns in growth. Our leverage standards are set to survive a 20–30% value decline without distressed sale. |
| We never acquire in a submarket without confirmed, current comparable rental data | Historical data can be misleading. We require active comparable rentals within 0.5 miles at our projected rent, closed within 90 days, before any acquisition is underwritten. |
| We never proceed if the physical inspection reveals undisclosed or unpriced structural issues | A distressed seller's disclosed condition and a professional inspector's discovered condition are frequently different. If the gap cannot be priced into the acquisition, we do not proceed. |
| We never waive the due diligence period to win a competitive bid | Speed should never come at the cost of diligence. A deal we lost because we completed due diligence is a deal we made the right decision on. |